Markets · Refined Products · Product Tankers
The global diesel shortage is no longer a short-lived regional squeeze. Inventories across the United States, Europe and Asia remain unusually low, diesel prices have reached record territory in major markets, and the U.S. Energy Information Administration expects distillate stocks to remain below normal levels through much of 2027.
The strongest warning signal is in the United States. Distillate inventories stood at 107.9 million barrels on September 11, the lowest level for this time of year since EIA records began in 1982. The agency expects stocks to fall below 100 million barrels and remain below the five-year low through most of 2027.
Global Diesel Shortage: The Key Numbers
| Indicator | Latest signal | Why it matters |
|---|---|---|
| U.S. distillate inventories | 107.9m barrels on 11 Sep | Lowest for this time of year since EIA records began in 1982 |
| EIA inventory outlook | Below 100m barrels; below five-year low through much of 2027 | Shows tightness may persist beyond winter |
| U.S. retail diesel | Above $6/gal in September | Direct inflationary pressure on trucking, farming and industry |
| U.S. diesel crack | $118.62/bbl on 14 Sep | Record refining margin encourages maximum diesel output |
| ARA inventories | 16% below five-year average in July | Europe remains dependent on imported middle distillates |
| Singapore distillates | ~8.2m barrels recently | Below 2025 average of 9.6m barrels |
| China diesel exports | 1.33m tonnes in August, +42.1% YoY | Potential relief source for tight global markets |
Why Diesel Is Tighter Than Crude Oil
A crude-oil market can be relatively well supplied while diesel remains scarce.
The reason is the refinery.
Crude oil must be processed into transport fuels, and the amount of diesel that can be produced depends on refinery availability, configuration, crude slate, maintenance schedules and the economics of competing products such as gasoline and jet fuel.
That makes refining capacity the critical bottleneck in the current market.
Supply disruption has hit some of the regions that normally export large volumes of middle distillates. The Middle East has faced major disruption to refined-product flows, while Russia has restricted diesel exports as refinery operations and domestic supply remain under pressure.
Reuters reported that Middle Eastern diesel shipments between March and August were roughly half the level seen in the comparable period a year earlier.
U.S. Diesel Stocks Are at a Historic Seasonal Low
EIA data show U.S. distillate stocks at 107.859 million barrels for the week ending September 11.
That compares with 106.274 million barrels one week earlier, but the small weekly build does not change the broader picture. Reuters reported that the level is the lowest for this point in the year since EIA records began in 1982.
The September EIA Short-Term Energy Outlook goes further.
The agency expects U.S. distillate inventories to fall below 100 million barrels and remain below the five-year 2021–2025 low through the end of 2026 and most of 2027.
EIA says global distillate production is expected to remain below last year’s levels in the coming months, supporting high U.S. diesel prices and stronger export incentives.
The Empty-Tank Paradox: More Storage Is Available Because There Is Less Diesel
One of the clearest signals of physical tightness is coming from the storage market.
North American and Caribbean diesel storage capacity available for lease is expected to reach around 13 million barrels in October, according to storage broker The Tank Tiger, up from approximately 11 million barrels in June.
Normally, more available tank space might suggest abundant supply.
Here it suggests the opposite.
Traders and refiners are allowing storage leases to expire because there is not enough diesel available to justify paying for the tanks.
That is important because storage contracts typically run for months. Rising availability today therefore reflects expectations that physical tightness could persist well into 2027.
Europe Is Entering Winter With Thin Diesel Inventories
Europe is particularly exposed because the region has become increasingly dependent on imported diesel after refinery closures and the loss of traditional Russian supply.
Reuters reported that diesel inventories in the Amsterdam–Rotterdam–Antwerp trading hub were 16% below the five-year average in July.
Independent ARA gasoil stocks fell to their lowest level in almost four years during July, according to Insights Global data cited by market sources.
That creates a familiar arbitrage pattern:
Europe short of diesel → European prices rise → arbitrage opens → Atlantic Basin and Asian barrels move toward Europe → product-tanker tonne-miles increase.
Tide Signal has already tracked the same mechanism in aviation fuel. See Europe’s jet fuel deficit and South Korean exports.
Asia Is Not Comfortable Either
Singapore’s total distillate stocks have recently averaged around 8.2 million barrels, according to data cited by Reuters.
That is below the 9.6 million-barrel average recorded in 2025.
Asian diesel markets have been less uniformly tight than Europe or the U.S., but that spare flexibility matters because Asia is one of the few regions capable of sending additional barrels into deficit markets.
The problem is that every extra long-haul export competes with regional demand and consumes ship capacity.
Record Diesel Crack Spreads Are Telling Refineries to Run Hard
The U.S. ultra-low-sulfur diesel crack spread — the premium of diesel futures over crude oil — reached a record $118.62 per barrel on September 14.
This is an extraordinary refining signal.
A high crack spread tells refiners that producing diesel is highly profitable.
Normally that encourages:
- higher refinery utilization;
- maximum middle-distillate yields where technically possible;
- deferred discretionary maintenance;
- stronger crude demand from complex refineries;
- greater incentive to export into premium markets.
But refining systems have physical limits. A refinery cannot simply double diesel output because the crack spread rises.
That is why record margins can coexist with a persistent shortage.
China Is Becoming the Most Important Relief Valve
China has begun increasing refined-product exports after earlier restrictions aimed at protecting domestic supply.
Official customs data reported by Reuters showed Chinese diesel exports at 1.33 million tonnes in August, up 42.1% year on year and the highest level since March 2024.
Total refined-fuel exports reached 6.01 million tonnes in August.
For the full China flow picture, see Tide Signal’s China Fuel Exports 2026 analysis.
China matters because its refining system has the scale to alter global balances.
If Beijing permits exporters to place more diesel into international markets, Asian barrels could provide partial relief to Europe, Africa and other deficit regions.
But that relief creates another shipping effect: longer-haul voyages from Northeast Asia to Europe or Africa can increase MR and LR tonne-mile demand.
What the Diesel Shortage Means for Product Tankers
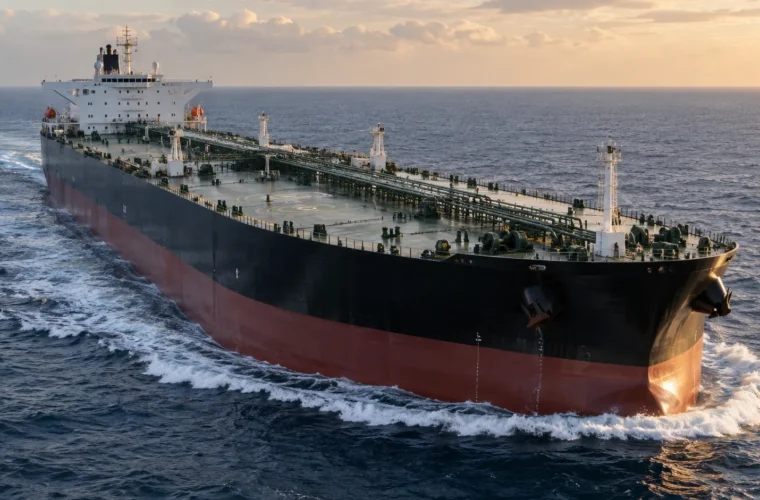
The relationship between diesel scarcity and tanker rates is not automatic, but the direction is commercially important.
A shortage can support product tanker demand through four mechanisms.
1. Replacement barrels travel farther
When a region loses its normal supplier, replacement cargoes often come from a more distant refinery system.
Europe replacing nearby Russian or Middle Eastern barrels with cargoes from the U.S. Gulf Coast, India, South Korea or China increases voyage distance.
2. Arbitrage creates more cargo opportunities
Large regional price differences create trading opportunities. If the delivered price spread exceeds freight, financing and handling costs, a cargo can move.
3. Longer voyages absorb vessel-days
A ship on a longer round voyage is unavailable to the spot market for longer. Even if global cargo volume is unchanged, tonne-mile demand can rise.
4. Volatility raises the value of prompt tonnage
When commodity spreads change quickly, charterers may pay more for ships positioned near the loading region and able to meet a narrow laycan.
For the freight mechanism behind these fixtures, see Tide Signal’s guide to Worldscale in shipping.
MR, LR1 or LR2: Which Tanker Segments Benefit?
| Segment | Typical role | Diesel-shortage relevance |
|---|---|---|
| MR | Regional and medium-haul clean products | Flexible replacement cargoes, Europe/Atlantic Basin, Asia regional trades |
| LR1 | Larger clean-product parcels | Longer-haul diesel and jet flows where parcel economics support larger stems |
| LR2 | Large long-haul refined-product cargoes | Major Middle East/Asia-to-Europe or Atlantic replacement flows |
The most bullish shipping outcome is not simply “diesel price up.” It is diesel shortage + open arbitrage + long-distance replacement barrels + limited vessel availability.
Why Europe–US and Asia–Europe Arbitrage Matters
Market reporting in September showed Europe seeking more diesel outside its traditional supply system, including Atlantic Basin and Asian sources.
For tanker markets, this changes the distance matrix.
A short regional cargo may require only a few vessel-days. A transatlantic or Asia–Europe cargo can absorb the same ship for several weeks including ballast, loading, discharge and repositioning.
That is why tonne-miles often matter more than tonnes.
Tide Signal has already seen this effect in Asia diesel exports to Africa, where the loss of nearby Middle Eastern supply shifted demand toward longer Asian voyages.
Winter Is the Next Stress Test
The Northern Hemisphere heating season adds another layer of risk.
Diesel and heating oil compete within the middle-distillate barrel.
As temperatures fall, heating demand can reduce the amount of material available for transport-fuel markets.
At the same time:
- U.S. East Coast buyers may build inventories;
- European heating demand can rise;
- refinery maintenance can temporarily remove capacity;
- weather can disrupt ports and shipping schedules;
- low inventories leave less protection against an outage.
That means the market enters winter with unusually little buffer.
What Could Ease the Global Diesel Shortage?
There are several routes to relief.
More Chinese exports
China can provide additional barrels if domestic policy and margins support exports.
Recovery in Middle East flows
A normalization of refinery and export operations would restore one of the world’s most important sources of middle distillates.
Russian refinery recovery
Higher refinery utilization and eventual relaxation of export restrictions could return additional diesel to international markets.
Demand destruction
Very high prices can reduce freight activity, industrial consumption and discretionary diesel use.
Strong refinery economics
Record crack spreads encourage refiners to maximize middle-distillate production wherever technically possible.
What Could Make the Shortage Worse?
The downside risks are equally clear.
- another major refinery outage;
- additional disruption in the Middle East;
- further attacks on Russian refining capacity;
- extended diesel export restrictions;
- severe winter weather;
- stronger-than-expected industrial or transport demand;
- shipping disruptions that delay replacement cargoes.
Because inventories are already low, the market has less ability to absorb any new shock.
The Diesel Market Is an Inflation Signal
Diesel sits deep inside the physical economy.
It powers:
- heavy trucks;
- agricultural machinery;
- construction equipment;
- mining vehicles;
- industrial generators;
- rail locomotives in many markets;
- parts of the marine and inland logistics system.
That means a diesel shock is transmitted through supply chains rather than remaining confined to motorists.
Higher diesel costs can increase the delivered price of food, manufactured goods, construction materials and almost any product moved by truck.
Market Signals to Watch Through Q4 2026
- U.S. distillate inventories: whether EIA stocks fall below 100 million barrels as forecast.
- U.S. diesel crack: whether the record $118.62/bbl margin remains elevated.
- ARA gasoil stocks: the size of Europe’s winter buffer.
- Singapore inventories: whether Asia can rebuild stocks while exporting more barrels.
- China export quotas and flows: the strongest potential supply relief valve.
- Russia export restrictions: whether full diesel exports resume.
- Middle East refinery exports: recovery would materially change the global balance.
- MR/LR freight: whether long-haul arbitrage translates into higher tanker earnings.
Frequently Asked Questions
Is there a global diesel shortage in 2026?
Yes. Inventories are unusually low across several major markets, while supply disruption from key export regions has contributed to record diesel prices and refining margins.
How low are U.S. diesel inventories?
U.S. distillate fuel inventories stood at 107.9 million barrels on September 11, 2026. Reuters reported this as the lowest level for this time of year since EIA records began in 1982.
Will the diesel shortage last into 2027?
The EIA expects U.S. distillate inventories to remain below the five-year low through much of 2027, while industry participants cited by Reuters expect global tightness to persist into next year.
Why are diesel prices so high?
The market is being squeezed by low inventories, constrained refinery output, reduced exports from important supply regions and strong competition for available middle-distillate barrels.
Can China solve the diesel shortage?
China can provide meaningful relief but is unlikely to solve the entire global deficit alone. August diesel exports rose to 1.33 million tonnes, the highest since March 2024, but global balances remain tight.
Is a diesel shortage good for product tanker rates?
It can be supportive when regional shortages open long-haul arbitrage routes and increase tonne-mile demand. The effect depends on commodity spreads, vessel supply, parcel size and freight costs.
Key Takeaways
- The global diesel shortage is increasingly likely to remain a major market theme into 2027.
- U.S. distillate inventories were 107.9 million barrels on September 11.
- EIA expects inventories below 100 million barrels and below the five-year low through much of 2027.
- ARA stocks were 16% below their five-year average in July.
- Singapore distillates near 8.2 million barrels remain below the 2025 average.
- The U.S. diesel crack reached a record $118.62/bbl.
- China’s August diesel exports rose 42.1% YoY to 1.33 million tonnes.
- Long-haul replacement trade can support MR, LR1 and LR2 tanker tonne-mile demand.
- The next major test is the Northern Hemisphere winter heating season.
Sources and Further Reading
- Reuters — Global diesel shortage likely to last into 2027 as storage tanks drain, 21 September 2026
- Reuters — Global diesel prices hit record highs, further rises possible, 21 September 2026
- U.S. EIA — Weekly Stocks of Distillate Fuel Oil
- U.S. EIA — September 2026 Short-Term Energy Outlook
- Reuters — China August refined-fuel exports, 18 September 2026
Editorial note: inventory and price data can change rapidly. Tide Signal distinguishes physical stocks, retail prices, crack spreads and tanker freight because they measure different parts of the refined-products market.