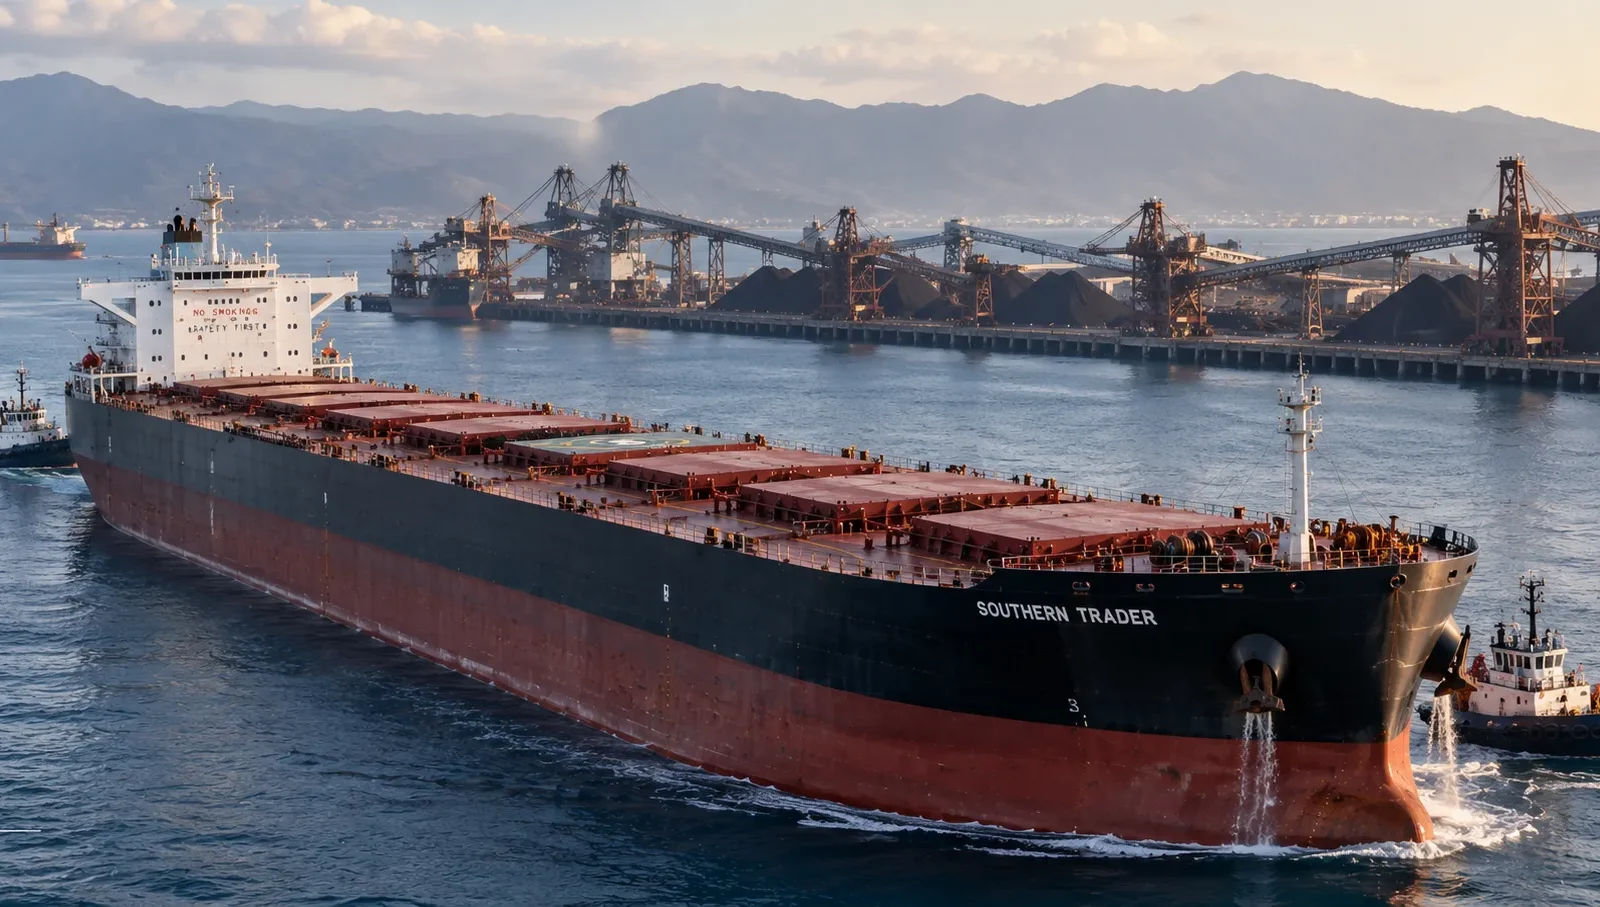
Dry bulk fleet capacity is tightening even as the number of bulk carriers continues to grow. New research from Ursa Shipbrokers, using AXSMarine tracking data for bulk carriers above 20,000 dwt, shows the average laden voyage lasted 22.42 days in June 2026 — 5.3% longer than a year earlier and 19.1% longer than in January 2020.
At the same time, bulk carriers are moving more slowly. Average laden speed stood at 10.67 knots in June, 2.2% below January 2020 and 9.4% below the August 2021 peak. Ballast speeds averaged 11.37 knots, 6.7% below their October 2021 peak.
The combination matters because shipping capacity is not determined only by how many ships exist. It is also determined by how much transport work each ship can complete over time.
A fleet can grow in physical numbers while tightening in commercial terms if voyages become longer, speeds fall, routing becomes less efficient, congestion absorbs vessel days or cargo origins shift farther from demand centres.
That is exactly the mechanism now becoming visible in dry bulk.
Source note: voyage-duration and speed data are from Ursa Shipbrokers analysis using AXSMarine tracking data as reported on 15 September 2026. The Capesize figure is from the Baltic Exchange Week 37 report published on 11 September 2026.
Dry Bulk Fleet Capacity: Why a Bigger Fleet Can Still Feel Tight
The simplest way to count shipping supply is to count ships.
But that is not the same as measuring effective dry bulk fleet capacity.
For a charterer, trader or operator, what matters is not merely whether a Capesize, Panamax or Supramax exists somewhere in the global fleet. The commercial question is whether the right vessel can reach the right loading area in the required window at an acceptable cost.
A vessel becomes less productive when it spends more time:
- sailing longer laden distances;
- ballasting farther between cargoes;
- rerouting around disrupted chokepoints;
- waiting at congested ports;
- slow steaming;
- avoiding security threats;
- waiting for weather or canal access; or
- repositioning because commodity trade patterns have changed.
None of those factors removes the ship from the fleet register.
But each one consumes vessel days.
Fleet size is a physical number. Fleet capacity is a time equation.
If the same cargo movement absorbs more ship-days than it did five years ago, effective supply can tighten even when new tonnage is entering the fleet.
Bulk Carrier Voyages Are 19.1% Longer Than in January 2020
The most striking number in the Ursa analysis is the change in voyage duration.
For bulk carriers above 20,000 dwt, the average laden voyage reached 22.42 days in June 2026.
That was:
- 5.3% longer year on year; and
- 19.1% longer than January 2020.
Every monthly reading during the first half of 2026 was also longer than the corresponding month in each of the previous six years, according to the reported analysis.
That suggests the increase is not simply the result of one unusually long month.
It reflects a structural shift in how dry bulk cargoes are moving.
What Does a 19% Longer Voyage Mean in Practice?
An average voyage-duration statistic is not a direct fleet-capacity calculation. Route mix changes, ballast time, port time, cargo sizes and vessel classes all matter.
But a simplified illustration shows why the direction is commercially important.
If 22.42 days is 19.1% above the January 2020 level, the implied earlier laden duration is roughly 18.8 days.
Purely as a mathematical illustration:
| Illustrative measure | January 2020 equivalent | June 2026 |
|---|---|---|
| Average laden voyage | ~18.8 days | 22.42 days |
| Theoretical laden legs / 365 days | ~19.4 | ~16.3 |
This is not an estimate that dry bulk fleet capacity has fallen by 16%. It deliberately excludes ballast voyages, port time, cargo operations, maintenance, off-hire and differences in route mix.
It simply demonstrates the mathematics: when each laden leg takes longer, the same vessel can complete fewer movements over the same calendar period.
Bulk Carriers Are Also Moving More Slowly
Longer distances are only one part of the capacity equation.
Ursa’s analysis also found average laden bulk-carrier speed of 10.67 knots in June 2026.
That was:
- 2.2% below January 2020; and
- 9.4% below the peak recorded in August 2021.
Average ballast speed was 11.37 knots, 6.7% below the October 2021 peak.
Small speed changes matter because shipping is a time-based business.
A vessel travelling 5,000 nautical miles at 12 knots has a theoretical sea time of about 17.4 days.
At 10.7 knots, the same distance takes about 19.5 days — more than two additional days before weather, routing allowances, port approaches or waiting time are included.
Tide Signal’s Voyage ETA Calculator allows readers to test how distance and average speed alter sea time, estimated arrival and optional bunker consumption.
Slow Steaming Is Not the Same as Weak Demand
Lower speed can be caused by several different commercial and operational factors.
Owners may slow steam to reduce bunker consumption.
Charterers may optimise voyage speed against fuel prices and cargo economics.
Ships may operate at lower speeds because of weather, hull condition, congestion, traffic schemes, engine limitations or environmental-performance targets.
That means slow steaming should not automatically be interpreted as evidence of weak demand.
In fact, slower ships can support freight by absorbing more ship-days.
This is one reason dry bulk markets can remain tight even when the fleet is expanding.
Longer Trading Distances Accelerated After 2023
The route-length story became more important from 2023 onward.
Ursa’s analysis identifies several major forces behind the shift:
- Panama Canal drought restrictions;
- Red Sea attacks and route avoidance;
- wars and sanctions;
- changes in commodity sourcing; and
- the resulting reorganisation of global trade patterns.
These events do not need to stop dry bulk trade to tighten shipping supply.
They only need to make the voyage longer.
Tonne-Mile Demand Is the Missing Variable in Many Dry Bulk Headlines
Cargo volume alone does not determine demand for shipping.
A tonne of iron ore shipped 1,000 nautical miles and a tonne shipped 10,000 nautical miles are both one tonne of cargo.
But they do not consume the same amount of ship capacity.
This is why shipping analysts focus on tonne-mile demand.
A simplified tonne-mile relationship is:
Cargo volume × transport distance = tonne-mile demand.
If cargo volume remains flat but average voyage distance increases, demand for vessel time can still rise.
That helps explain why freight markets sometimes strengthen even when macroeconomic cargo-growth headlines appear modest.
Dry Bulk Rates Are Reflecting the Capacity Tightness
The latest freight market provides supporting evidence.
The Baltic Exchange reported that the Capesize 182 5TC ended Week 37 at $55,139 per day. Earlier in September it moved above $58,000 per day, reaching a fresh year-to-date high.
The Baltic Dry Index ended 11 September at 3,507 points.
The market is not moving in a straight line. The latest Capesize week was mixed, with Pacific volatility and softer late-week sentiment, while the Atlantic remained comparatively steady.
That is important because strong effective-capacity fundamentals do not eliminate short-term freight corrections.
Cargo timing, miner participation, ballaster lists and regional position counts can still move rates sharply from day to day.
The structural story and the daily market are related, but they are not identical.
Why Capesize Freight Is Especially Sensitive to Voyage Length
Capesizes are heavily exposed to long-haul commodity trades, particularly iron ore and coal.
Because these ships carry large cargoes over long distances, route changes can absorb significant vessel time.
A change in the balance between:
- Australia–China;
- Brazil–China;
- West Africa–China;
- Atlantic round voyages; and
- long-haul coal flows
can materially affect the number of Capesize ships available in each basin.
A longer Brazil or West Africa programme can support tonne-mile demand even if Chinese import volumes are not accelerating at the same rate.
This is why charterers monitor ballaster counts and regional position lists as closely as global fleet statistics.
The Physical Fleet Can Grow While the Position List Shrinks
Consider two market statements:
“The dry bulk fleet grew this year.”
and:
“There are fewer prompt ships available for this cargo.”
Both can be true.
The first is a fleet-supply statistic.
The second is a chartering-market reality.
A position list can tighten because ships are:
- on longer voyages;
- delayed at discharge;
- ballasting from farther away;
- trading in another basin;
- fixed forward;
- waiting for weather;
- committed under period employment; or
- avoiding a route for security or commercial reasons.
This is why effective fleet capacity is often more useful than headline fleet growth when explaining short- and medium-term freight strength.
Panama Canal Restrictions Changed the Geometry of Trade
The Panama Canal drought demonstrated how infrastructure constraints can increase shipping demand without creating additional cargo.
When transit restrictions make a shorter route less reliable or less economical, ships may:
- wait for a slot;
- reduce cargo to meet draft restrictions;
- reroute around Cape Horn;
- change cargo origin; or
- use a different vessel class.
Each response alters the amount of vessel time needed to move trade.
Even after the immediate canal crisis eases, trade patterns and commercial habits do not necessarily return instantly to their earlier configuration.
Red Sea Disruption Has the Same Capacity Effect
Security problems around the Red Sea and Bab el-Mandeb have created a similar mechanism.
A vessel avoiding the normal route may sail farther around the Cape of Good Hope.
The cargo still arrives.
The fleet still contains the same ship.
But more ship-days are consumed.
This is the same effective-capacity mechanism Tide Signal recently highlighted in its ClarkSea Index analysis: current shipping earnings are being supported not only by cargo demand but by a global transport system using more vessel time to complete trade.
Commodity Sourcing Can Matter More Than Commodity Volume
Dry bulk trade is particularly exposed to changes in cargo origin.
If a buyer replaces a nearby source with a farther source, tonne-mile demand can rise even if imported tonnage does not.
Examples can include changes in:
- iron ore sourcing;
- coal origins;
- grain export corridors;
- bauxite flows;
- minor-bulk trade; and
- sanctions-driven commodity substitutions.
For owners, the most valuable demand growth is often not more tonnes.
It is more miles per tonne.
Why the BDI Alone Cannot Explain the Current Dry Bulk Market
The Baltic Dry Index is one of the most widely followed shipping-market indicators, but it is an outcome measure rather than a complete explanation.
The BDI is a composite of the Baltic Exchange’s Capesize, Panamax and Supramax time-charter averages.
According to the Baltic methodology:
- Capesize carries a 40% weighting;
- Panamax carries 30%; and
- Supramax carries 30%.
A higher BDI tells the market that dry-bulk freight assessments have strengthened.
It does not by itself explain whether the driver is:
- cargo growth;
- longer voyages;
- slow steaming;
- port congestion;
- weather;
- regional tonnage scarcity;
- commodity sourcing; or
- some combination of those factors.
That is why this article targets dry bulk fleet capacity rather than trying to become another BDI page.
Dry Bulk Fleet Capacity vs Fleet Growth
| Measure | What it captures | What it can miss |
|---|---|---|
| Fleet size | Number of ships / deadweight capacity | Voyage duration, congestion, route inefficiency |
| Fleet growth | Deliveries minus removals | How productively new ships are employed |
| Effective fleet capacity | Available transport work over time | Harder to reduce to one headline number |
| Tonne-mile demand | Cargo volume multiplied by distance | Port time, speed and ballast inefficiency |
Longer Voyages Change Voyage Economics
A longer voyage does not simply increase the number of days at sea.
It changes the commercial estimate.
For a voyage-charter owner, longer distance can increase:
- bunker consumption;
- time exposure;
- weather risk;
- crew and operating-day exposure;
- opportunity cost;
- carbon-related costs on applicable trades; and
- the uncertainty around the next fixture.
That means the freight rate needed to produce an acceptable return can rise even if port costs and cargo quantity remain unchanged.
Tide Signal’s Voyage Margin Calculator can be used to test how freight revenue changes after commissions and voyage costs, while the Voyage ETA Calculator shows how speed and distance alter sea time.
Voyage Charter and Time Charter Feel Longer Voyages Differently
The capacity effect also interacts with charterparty structure.
Under a voyage charter, the owner is normally pricing the voyage and carrying the main bunker and voyage-expense exposure, subject to the contract.
Under a time charter, the charterer normally carries bunkers and voyage expenses while paying daily hire to the owner.
A longer route therefore changes the economics differently depending on who controls employment and who pays the voyage costs.
Tide Signal’s Types of Charter Parties guide explains how voyage, time, bareboat and COA structures allocate vessel time, costs and market risk.
Slow Steaming Can Support Rates — But It Also Has Limits
Slow steaming has a useful market effect for owners because it absorbs capacity.
But a vessel cannot simply slow indefinitely.
Commercial limits include:
- laycan commitments;
- charterparty speed obligations;
- cargo urgency;
- weather windows;
- port schedules;
- engine operating limits;
- fuel quality;
- hull and propeller condition; and
- the value of the next fixture.
The optimal speed is therefore a commercial calculation, not simply “as slow as possible”.
Environmental Regulation Can Reinforce the Speed Trend
Lower speeds can also reduce fuel consumption and emissions per unit of time, although the full carbon effect depends on voyage duration, cargo carried, weather and machinery efficiency.
Regulation such as CII and EEXI has increased the industry’s focus on speed, power and operational efficiency.
For an older vessel, reducing speed can sometimes be part of the operational response to carbon-intensity pressure.
But there is a market trade-off:
what improves one ship’s fuel and emissions profile can reduce the amount of transport capacity available from the fleet over a year.
Congestion Can Tighten Capacity Without Changing Sailing Distance
Distance is not the only way vessel productivity falls.
A ship waiting five days outside a port has lost five ship-days even if its sea route has not changed.
Port congestion therefore creates the same broad capacity effect as rerouting:
more time is required to complete the cargo movement.
This is why operators should monitor:
- anchorage queues;
- berth productivity;
- weather delays;
- draft restrictions;
- labour disruptions;
- cargo readiness; and
- terminal operating windows.
A strong dry bulk market can be created by many small inefficiencies accumulating across thousands of voyages.
Why the 2026 Dry Bulk Market Is Not Simply a Demand Story
It would be easy to look at $55,000-plus Capesize earnings and conclude that cargo demand alone must be booming.
The data suggest a more complicated market.
Freight is being supported by the interaction of:
- commodity demand;
- longer trading distances;
- slower vessel speeds;
- geopolitical rerouting;
- sanctions-related trade changes;
- regional vessel positioning; and
- port and infrastructure constraints.
That distinction matters because different drivers have different durability.
A new iron-ore mine can create long-lived cargo demand.
A temporary canal restriction can disappear.
A structural sourcing shift can persist for years.
A war-related rerouting can reverse suddenly.
An owner deciding whether to buy, charter or order ships needs to know which type of tightness is supporting the market.
Why This Matters for Shipowners
For owners, tightening effective capacity can improve freight and utilisation.
But it also changes operating exposure.
Longer voyages can mean:
- more bunker consumed per cargo;
- more time exposed to weather;
- greater uncertainty over the next open date;
- more working capital tied to each voyage;
- higher opportunity cost if the market moves while the ship is committed; and
- greater sensitivity to performance and fuel efficiency.
The owner with an efficient vessel can therefore gain twice: from stronger freight and lower cost per day or mile relative to less efficient competitors.
Why This Matters for Charterers
For charterers, longer voyage cycles reduce flexibility.
A cargo that needs a prompt vessel may face a smaller effective position list.
That can lead to:
- higher freight bids;
- less choice between owners;
- greater need to fix forward;
- more exposure to laycan risk;
- higher cost for optionality; and
- greater importance of accurate ETA and position data.
Charterers therefore need to follow not only cargo lists but vessel geography and expected open dates.
Why This Matters for Operators
For operators trading ships in and out, longer voyage duration can materially alter the spread between charter-in hire and voyage earnings.
A voyage that looks profitable at 20 days can become much less attractive at 24 days if the operator is paying daily hire throughout the period.
That is particularly important when the market is volatile.
Four additional days can mean:
- four more days of charter-in hire;
- additional bunkers;
- a later redelivery;
- loss of the next cargo; or
- exposure to a market correction before the ship reopens.
Why This Matters for Investors
Investors should be careful with simple fleet-growth models.
A forecast that says “dry bulk supply grows X%” can be directionally correct and still miss market tightness if tonne-mile demand and voyage duration are rising faster.
Useful questions include:
- How fast is the fleet growing?
- How fast is tonne-mile demand growing?
- Are average voyage distances increasing?
- Are ships slowing down?
- Is congestion rising or falling?
- Where are new ships being delivered?
- Which basins are short of prompt tonnage?
- How quickly could disrupted routes normalise?
The answer to those questions can be more important than headline deadweight growth.
The Link to the Record ClarkSea Index
The dry bulk capacity story fits into the broader 2026 shipping market.
The ClarkSea Index has reached a record $56,567 per day, reflecting extraordinarily strong cross-sector shipping earnings.
Tankers are leading the current record, but dry bulk is providing meaningful support.
The common mechanism across sectors is increasingly clear:
geopolitical and operational friction is reducing the productivity of the world fleet.
In tankers, that can mean owners refusing risky routes.
In containers, it can mean longer diversions.
In dry bulk, it can mean longer voyages, slower speeds and changing commodity origins.
Different market.
Same capacity principle.
Could Dry Bulk Fleet Capacity Loosen Again?
Yes.
Effective capacity is dynamic.
It could loosen if:
- average voyage distances shorten;
- Red Sea routes normalise;
- Panama Canal constraints ease further;
- vessel speeds increase;
- port congestion falls;
- commodity sourcing shifts toward shorter routes;
- newbuilding deliveries accelerate; or
- cargo demand weakens.
The key risk for owners is that some of today’s capacity absorption is disruption-driven.
If disruption unwinds quickly, ships can effectively return to the market without a single newbuilding being delivered.
Could Effective Capacity Tighten Further?
It could also tighten further.
Potential catalysts include:
- more long-haul Atlantic-to-Asia cargoes;
- additional Red Sea disruption;
- new sanctions that alter commodity sourcing;
- weather disruptions in major export regions;
- port congestion;
- further reductions in average speed; and
- stronger iron ore, coal, grain or bauxite tonne-mile demand.
In that scenario, freight can remain strong even if fleet growth looks comfortable on paper.
What to Watch Next in the Dry Bulk Market
- Average laden voyage duration: whether the 22-day-plus level persists into the second half of 2026.
- Laden and ballast speeds: a sustained speed increase would release capacity.
- Capesize 5TC: whether earnings can hold above the $50,000/day area.
- Brazil and West Africa to China: long-haul iron-ore flows have strong tonne-mile impact.
- Pacific miner activity: important for near-term Capesize position lists.
- Red Sea and Panama routing: changes can release or absorb vessel days quickly.
- Port congestion: waiting time is hidden fleet absorption.
- Fleet deliveries: new tonnage only loosens the market if it adds capacity faster than voyage inefficiency absorbs it.
The dry bulk fleet does not need to shrink for shipping capacity to disappear.
A ship that takes longer to complete a voyage, sails more slowly, waits longer in port or travels farther between cargoes contributes less annual transport work than the same ship operating in a more efficient network.
That is why fleet growth alone is no longer enough to explain dry bulk supply. In 2026, time itself has become one of the market’s most important capacity constraints.
Dry Bulk Fleet Capacity FAQ
What is dry bulk fleet capacity?
Dry bulk fleet capacity is the amount of transport work the bulk-carrier fleet can make available to the market. It depends not only on the number and deadweight of ships but also on voyage distance, vessel speed, port time, ballast positioning, congestion and operational availability.
How long is the average dry bulk laden voyage in 2026?
Ursa Shipbrokers analysis using AXSMarine tracking data found an average laden voyage duration of 22.42 days in June 2026 for bulk carriers above 20,000 dwt.
How much longer are dry bulk voyages than in 2020?
The June 2026 average was reported to be 19.1% longer than in January 2020 and 5.3% longer than a year earlier.
How fast are bulk carriers sailing?
Average laden speed was reported at 10.67 knots in June 2026, 2.2% below January 2020 and 9.4% below the August 2021 peak. Average ballast speed was 11.37 knots.
Why do longer voyages increase dry bulk freight rates?
Longer voyages absorb more vessel days. If each cargo movement keeps a ship occupied for longer, fewer ships are available for new cargoes at any given time, which can tighten position lists and support freight.
What is tonne-mile demand in dry bulk shipping?
Tonne-mile demand combines cargo volume with transport distance. One tonne carried over a longer route creates more shipping demand than one tonne carried over a short route.
Why can the dry bulk market be tight while the fleet is growing?
Fleet growth measures physical supply. Effective capacity can still tighten if voyage distances increase, speeds fall, congestion absorbs time or ships need longer ballast positioning between cargoes.
What is the current Capesize rate?
The Baltic Exchange’s Capesize 182 5TC ended Week 37 on 11 September 2026 at $55,139 per day after trading above $58,000 per day earlier in September. Daily assessments can change materially.
Is the Baltic Dry Index the same as dry bulk fleet capacity?
No. The Baltic Dry Index measures assessed dry-bulk freight conditions across Capesize, Panamax and Supramax markets. Fleet capacity describes the transport work available from the fleet and helps explain why freight may tighten or loosen.
For the fleet-supply side of the dry-bulk market, see Tide Signal’s dry bulk fleet capacity.
The supply-side context is covered in Tide Signal’s Baltic Dry Index 2026.
Does slow steaming reduce fleet capacity?
Yes, all else equal. Lower speed means a vessel requires more time to complete a voyage, which reduces the number of voyages it can theoretically perform over a fixed period. Actual market capacity also depends on ports, ballast time, cargo demand and route mix.
Sources and Further Reading
- Splash — Slow ships and long voyages tighten dry bulk market, 15 September 2026
- Baltic Exchange — Bulk Report, Week 37
- Baltic Exchange — Dry bulk indices, routes and methodology
- AXSMarine — Dry bulk market intelligence and vessel-tracking platform
- AXSMarine AXSDry — Dry bulk chartering and market data