Markets · Trade · Dry Bulk · Thermal Coal
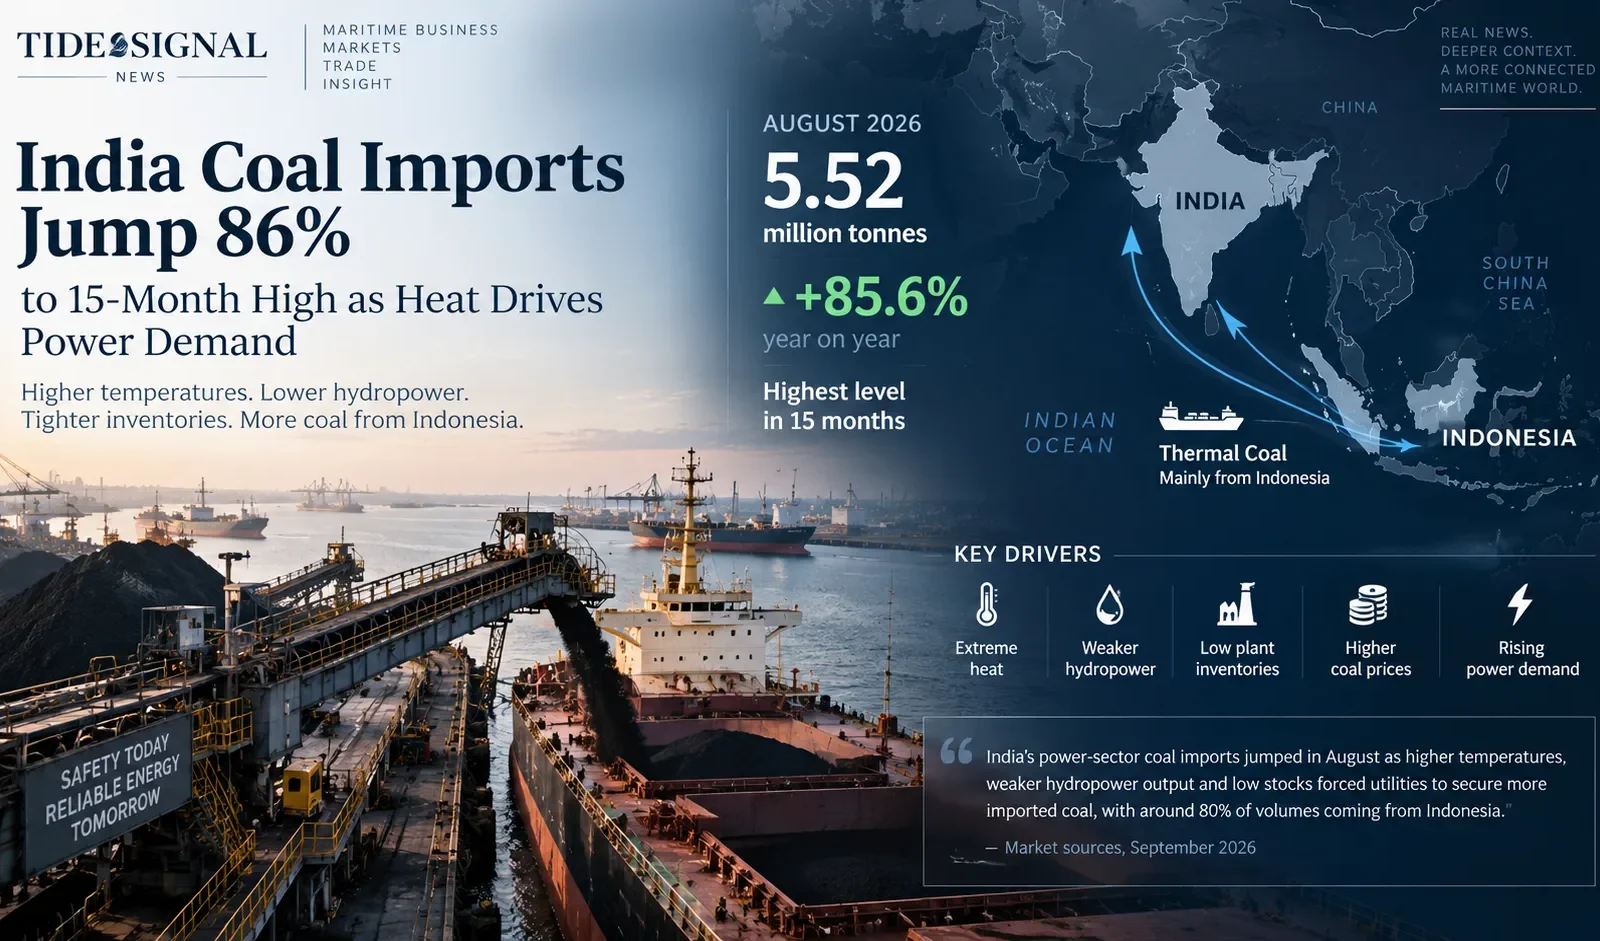
India coal imports by the power sector surged 85.6% year on year to 5.52 million tonnes in August, the highest level in 15 months. A heatwave, weaker hydropower generation and rapidly tightening fuel inventories pushed utilities back into the seaborne thermal-coal market even as imported coal became more expensive.
Electricity consumption rose faster than domestic coal supply in August. Heat-driven cooling demand increased power burn, lower hydropower generation reduced an important alternative source of electricity, and limited battery storage meant daytime solar generation could not fully cover evening and night demand. Domestic coal dispatch to the power sector rose by only 2.3 million tonnes while consumption increased by around 10 million tonnes, leaving utilities to fill part of the gap with imported thermal coal.
India Coal Imports Jump 85.6% as Electricity Demand Surges
Indian power producers imported 5.52 million tonnes of coal in August 2026, up 85.6% from a year earlier and the highest monthly total since May 2025, according to local trader iEnergy Natural Resources data reported by Reuters.
August was the third consecutive month of higher utility coal imports. The immediate driver was electricity demand. Prolonged heat increased cooling load at the same time hydropower generation weakened, forcing thermal plants to burn more fuel.
The supply side did not expand fast enough. Reuters reported that domestic coal dispatch to the power sector rose by only 2.3 million tonnes in August, while consumption increased by around 10 million tonnes.
↓
MORE COOLING DEMAND
↓
WEAKER HYDROPOWER + LIMITED STORAGE
↓
HIGHER COAL-FIRED GENERATION
↓
DOMESTIC DISPATCH LAGS CONSUMPTION
↓
MORE IMPORTED THERMAL COAL
Coal Stocks at Indian Power Plants Have Tightened Sharply
The import surge followed a sharp deterioration in plant-level fuel inventories. Reuters reported that 45 coal-fired power plants had critically low coal stocks as of 25 August, up from 31 at the end of July.
Industry data cited by Reuters put total reserves around 30.95 million tonnes, enough for roughly 10 days of burn at the time. Heavy monsoon disruption in major producing states affected mining and transportation, while some generating stations also faced inadequate railway deliveries.
This highlights a crucial distinction: India can have huge national coal resources while individual power plants still face local shortages because the right fuel is not at the right plant at the right time.
Tide Signal analysis
Coal availability is a logistics question as much as a production question. Mine output, pithead stocks, rail capacity, port handling and plant inventories are separate links in the chain. A record national production forecast does not automatically prevent plant-level shortages.
Indonesia Supplied About 80% of India’s August Utility Coal Imports
About 4.2 million tonnes of the 5.52 million tonnes imported by Indian power producers in August came from Indonesia — roughly 80% of the total.
Indonesia is a natural supplier because of its scale, proximity, established utility relationships and broad range of thermal coal qualities. The trade also supports several dry-bulk vessel classes, including Supramax, Ultramax and Panamax tonnage depending on terminal restrictions, parcel size and draft.
4.2m ÷ 75,000 tonnes ≈ 56 Panamax-sized cargoes4.2m ÷ 55,000 tonnes ≈ 76 Supramax-sized cargoesThese are illustrations rather than actual fixture counts. Real intake depends on vessel deadweight, draft, bunker quantity, cargo density and port limits.
The calculation shows why a national power-market shift can quickly become a shipping-market signal. Millions of additional tonnes create dozens of possible vessel employments.
India Is Buying More Imported Coal Just as Prices Rise
The timing is commercially difficult. Traders cited by Reuters said that since May, Indonesian coal prices had risen about 18%–20%, South African coal around 19% and Russian coal around 14%.
Delivered cost includes much more than the mine price: ocean freight, insurance, handling, quality adjustment, financing, port costs and inland transportation all matter.
If buyers shift from nearby Indonesia to longer-haul origins such as South Africa or Russia, the coal itself may be competitive but the shipping component becomes larger.
What India Coal Imports Mean for Dry-Bulk Shipping
For owners and charterers, the key question is not simply how many tonnes India imported. It is where those tonnes load, where they discharge, which vessel sizes can be used and how long the ships remain tied up.
The August surge can support dry-bulk demand through:
- more Indonesia–India coal cargoes;
- higher Supramax and Panamax employment;
- more ballast demand into Southeast Asia;
- tighter Indian Ocean tonnage lists;
- additional tonne-mile demand if India buys from longer-haul origins;
- possible discharge-port pressure if imports stay elevated.
Tide Signal’s Dry Bulk Fleet Capacity analysis explains why effective ship supply can tighten when voyages become longer or vessels spend more time waiting.
Panamax vs Supramax: Which Segment Benefits?
| Segment | Typical role | Potential advantage | Constraint |
|---|---|---|---|
| Panamax / Kamsarmax | Larger utility parcels | Lower transport cost per tonne on suitable ports | Draft and berth limits |
| Supramax / Ultramax | Flexible Indonesia–India parcels | Wider port access and regional flexibility | Less scale economy than Panamax |
| Handysize | Smaller parcels or restricted terminals | High port flexibility | Less efficient for large programmes |
Indonesia–India can be particularly relevant to geared Supramax and Ultramax vessels because many Indonesian loading operations rely on offshore transshipment or terminals where geared tonnage is useful. Larger Panamax and Kamsarmax ships remain important where infrastructure and cargo volumes allow.
Will India Coal Imports Push the Baltic Dry Index Higher?
Potentially, but not by themselves. The Baltic Dry Index reflects a broad mix of Capesize, Panamax and Supramax routes.
Higher Indian thermal-coal buying can support Panamax and Supramax demand in Asia, Indonesia–India freight, South Africa–India tonne-miles and vessel positioning in the Indian Ocean. But the broader BDI also depends on Chinese iron ore, Brazilian exports, grain trade, global coal demand, fleet supply and congestion.
The first place to watch is regional Panamax and Supramax freight, not the headline BDI. If India keeps buying more Indonesian coal for several months, fixture activity and tonnage lists should show the pressure before a global composite index fully reflects it.
Why Is India Importing More Coal If Domestic Production Is Rising?
The International Energy Agency expects India’s coal production to reach a record 1,095 million tonnes in 2026. Yet power-sector imports jumped sharply in August. Both facts can be true.
Imports can rise temporarily because of:
- domestic dispatch shortages;
- rail bottlenecks;
- weather disruption at mines;
- specific quality requirements;
- rapid electricity-demand spikes;
- low inventories at individual plants.
The Indian Ministry of Coal notes that consumers may import coal under the country’s Open General Licence according to commercial need. Imports therefore act partly as a balancing tool when the domestic logistics chain is under pressure.
IEA: India Coal Demand Is Expected to Rise 4.2% in 2026
The IEA’s Coal Mid-Year Update 2026, published on 10 September, expects India’s coal demand to rise 4.2% to 1,353 million tonnes this year.
The agency says electricity demand will continue to support coal consumption despite rapid renewable expansion. El Niño conditions can increase cooling demand while reducing hydropower availability, and industrial demand remains strong in pig iron, direct reduced iron and cement.
But the annual trade outlook adds an important nuance: the IEA still expects India’s thermal-coal imports to fall to around 160 million tonnes in 2026 from 167 million tonnes in 2025 as domestic supply and import substitution reduce requirements over the year.
Tide Signal analysis
There is no contradiction between a lower full-year import forecast and an 85.6% August surge by utilities. One is an annual national trade trend; the other is a sharp monthly response by the power sector. If domestic logistics recover and weather pressure eases, utility imports can fall again even while total coal consumption continues to rise.
The Global Coal Market Is Being Repriced by the Energy Crisis
The IEA now expects global coal demand to rise 1.2% in 2026 to a record 8.94 billion tonnes, reversing its previous expectation for a decline.
Higher natural-gas prices are one of the drivers. Coal is a substitute for gas in several power markets, and the loss of large LNG volumes through the Strait of Hormuz has increased the incentive for gas-to-coal switching.
India’s August surge was primarily about heat, hydropower and domestic logistics, but the global fuel backdrop still matters. Tide Signal’s LNG Prices 2026 analysis explains why Asian LNG near $26–$30/mmBtu is forcing price-sensitive buyers to reconsider alternative fuels.
Why Tonne-Miles Matter More Than Tonnes Alone
A tonne of coal from Indonesia does not create the same shipping demand as a tonne from South Africa or Russia. Longer voyages absorb more vessel days, which is why dry-bulk markets focus on tonne-mile demand, not cargo volume alone.
If India’s incremental imports remain overwhelmingly Indonesian, the volume effect may be large but voyage lengths relatively short. If buyers increasingly source longer-haul cargoes, the same number of tonnes can create much more vessel demand.
Coal purchase price + ocean freight + insurance + port costs + inland logistics + quality adjustment = delivered fuel costFor the voyage side, see Tide Signal’s Voyage Estimation in Shipping.
Could Coal-Port Congestion Become the Next Risk?
A concentrated wave of utility buying can create pressure at Indian discharge ports if several buyers rebuild inventories simultaneously. The potential effects are longer anchorage waiting, higher demurrage exposure, slower vessel turnaround and reduced effective fleet supply.
There is no evidence in the current data of a uniform nationwide coal-port congestion crisis. It is simply a key indicator to watch if India coal imports stay high through September and October.
Tide Signal’s Port Delays guide explains why waiting time can turn strong cargo demand into a vessel-capacity problem.
What to Watch Next
- September utility imports: does the August surge continue?
- Power demand: persistent heat keeps cooling load high.
- Hydropower: stronger hydro output could reduce thermal burn.
- Plant inventories: do critical stocks rebuild?
- Domestic rail dispatch: improved mine-to-plant logistics can reduce imports.
- Indonesian coal prices: another rise can weaken import economics.
- Indonesia–India freight: the clearest direct shipping signal.
- Panamax/Supramax tonnage lists: watch for tightening vessel availability.
- South Africa–India cargoes: more long-haul supply would raise tonne-miles.
- LNG prices: expensive gas can continue supporting coal demand.
- BDI segment rates: watch whether coal pressure spreads into wider benchmarks.
India Coal Imports 2026 FAQ
How much coal did Indian power producers import in August 2026?
India’s power sector imported 5.52 million tonnes of coal in August, according to iEnergy data reported by Reuters.
How much did India coal imports increase?
Power-sector coal imports rose 85.6% year on year in August 2026, reaching their highest level since May 2025.
Which country supplied most of India’s imported power coal?
Indonesia supplied about 4.2 million tonnes, or roughly 80% of the August total.
Why did India import more coal?
Heat-driven electricity demand, weaker hydropower generation, insufficient domestic dispatch growth and low inventories at many coal-fired plants increased the need for overseas supply.
Is India running out of coal?
No. India has very large domestic production and the IEA expects output to reach a record 1,095 million tonnes in 2026. The immediate issue is plant-level inventory and logistics pressure rather than a national absence of coal resources.
How much coal will India consume in 2026?
The IEA expects India’s coal demand to increase 4.2% to around 1,353 million tonnes.
Will India’s coal imports keep rising all year?
Not necessarily. The IEA still projects India’s thermal-coal imports at around 160 million tonnes in 2026, down from 167 million tonnes in 2025. The August power-sector spike may ease if domestic supply and stocks recover.
What does the import surge mean for dry-bulk shipping?
It creates additional cargo demand for Panamax, Kamsarmax, Supramax and Ultramax vessels, particularly on Indonesia–India routes. Longer-haul sourcing can create even more tonne-mile demand.
Does higher India coal demand automatically lift the BDI?
No. It can support some dry-bulk segments, but the Baltic Dry Index also depends on iron ore, grain, global coal trades, fleet supply, congestion and multiple other routes.
- Reuters — Indian utilities’ August coal imports surge to 15-month high
- Reuters — 45 Indian coal power plants have critically low fuel stocks
- IEA — Coal Mid-Year Update 2026: Demand
- IEA — Coal Mid-Year Update 2026: Trade
- IEA — Coal Mid-Year Update 2026: Production
- India Ministry of Coal — Monthly Statistics at a Glance
- India Ministry of Coal — Coal Import and Export Statistics
Editorial note: The 85.6% figure refers specifically to August coal imports by India’s power sector, not total national coal imports. Import volumes, plant stocks, freight rates and coal prices can change quickly. Tide Signal will update this page as new September trade and power-sector data become available.